Every month, most registered shop owners in India claim input tax credit only after they finish gstr 2b reconciliation. GSTR-2B is the auto-drafted ITC statement on the GST portal that shows what your suppliers have reported for you. Your purchase register shows what you booked in the billing software. Matching those two lists — invoice by invoice — is what keeps ITC clean and avoids last-minute surprises when you file GSTR-3B.
This guide walks through a practical monthly process for retailers: how to download 2B, how to match supplier invoices, the gaps you will see most often (late-filing suppliers, wrong GSTIN, credit notes), and why clean purchase entries in billing software make the whole job faster. It is for shop owners and accounts staff — not a substitute for advice from your CA or GST practitioner.
What GSTR-2B is (and what it is not)
GSTR-2B is a static statement generated on the GST portal for a tax period. It reflects invoices, debit notes and credit notes that your suppliers have filed in their GSTR-1 (or IFF under QRMP) for that period, plus other documents the portal includes for ITC. You do not file 2B; you read it.
It is different from GSTR-2A (which updates as suppliers keep filing) and different from GSTR-3B (which is your summary return where you actually claim ITC and pay tax). For a plain overview of how sales returns and the summary return relate, see our note on GSTR-1 vs GSTR-3B. For the credit rules themselves, see what is input tax credit in GST.
Official portal access and return guides are on gst.gov.in. Rate and circular references live on cbic.gov.in.
Why retailers need a monthly GSTR-2B reconciliation routine
ITC is not automatic just because you paid a supplier. Your books must show a valid tax invoice, the goods or services must be received, the tax must be paid to the government through the supplier’s return, and the credit must appear (or be eligible) as per the law and portal statement you rely on for that month. When books and 2B disagree, three things happen:
- You may claim too much ITC and face interest or notices later.
- You may claim too little and leave cash stuck until a later month.
- You waste hours chasing invoices that never appear because of a GSTIN or invoice-number typo.
A fixed monthly routine — usually in the first half of the next month after suppliers’ due dates — turns this into a checklist instead of a scramble.
GSTR-2B reconciliation: step-by-step monthly process
Use this sequence for a single GSTIN shop. Multi-branch groups should run it per GSTIN, then roll up.
1. Freeze the purchase books for the period
In your billing or purchase module, close the tax period. Export (or print) every purchase tax invoice, debit note and credit note that you booked for that month — B2B only for 2B matching. Include the supplier GSTIN, invoice number, invoice date, taxable value, CGST, SGST, IGST and cess if any. If your team still posts purchases from WhatsApp photos into a notebook, fix that first; reconciliation cannot fix missing entries.
Clean purchase workflows are covered in retail purchase management software.
2. Download GSTR-2B for the same period
On the GST portal, open Returns → GSTR-2B for the tax period and download the JSON or Excel the portal offers. Keep one folder per month (for example FY2026-27/2026-10/2B). Do not mix provisional screenshots with the final download you used for filing.
3. Match on the four keys that matter
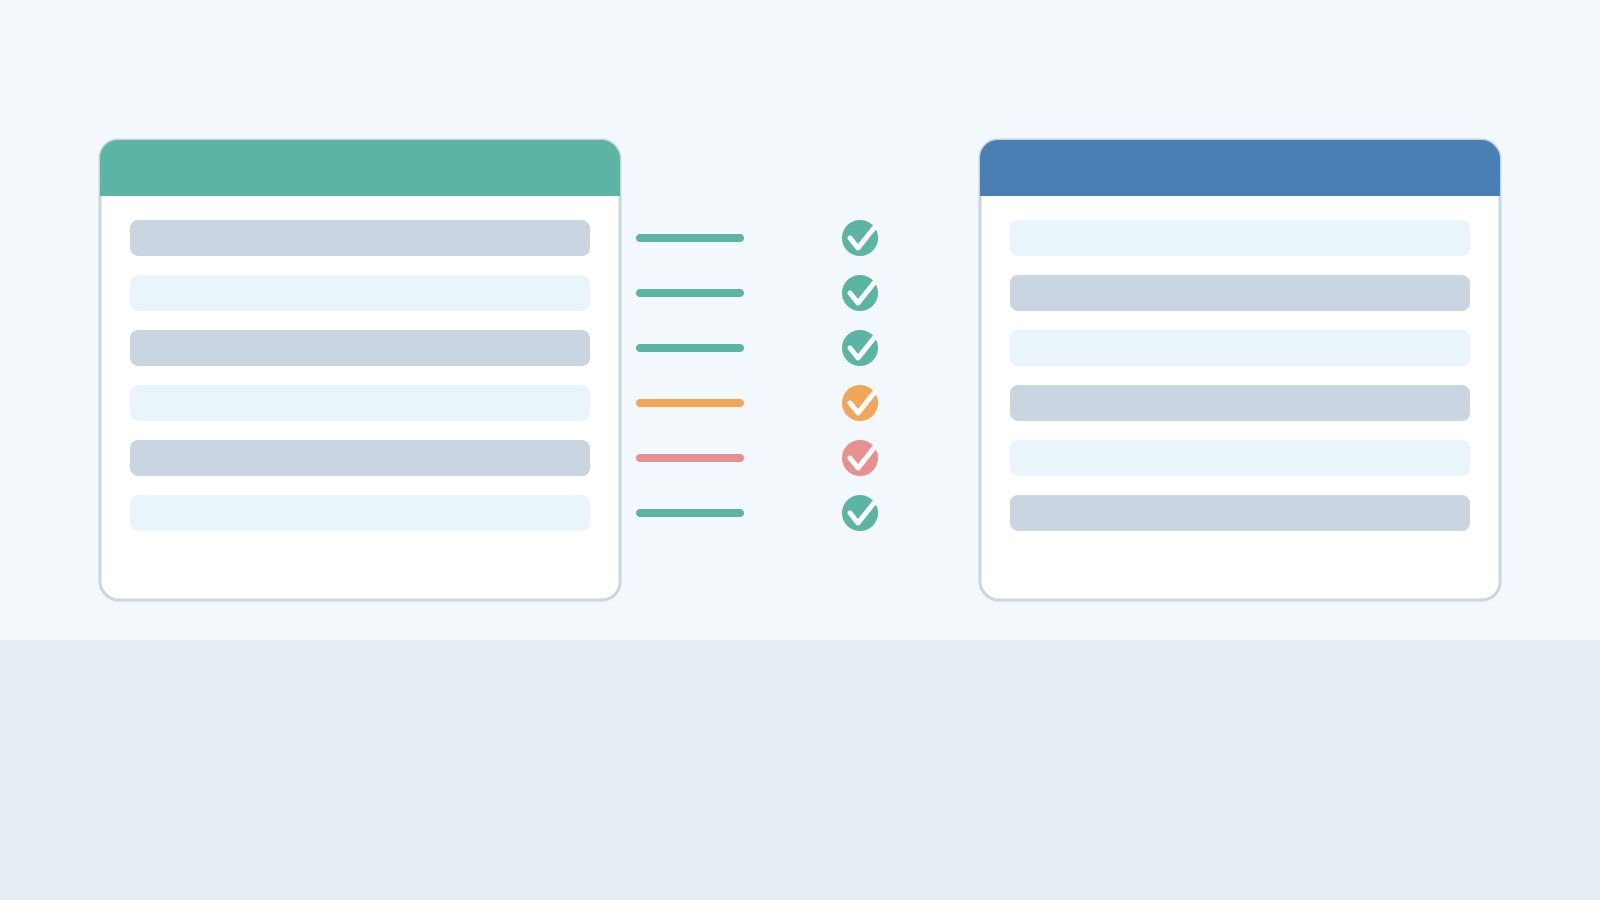
Match each books line to a 2B line using, in order:
- Supplier GSTIN
- Invoice (or note) number
- Invoice date (or at least the same month/year)
- Taxable value and tax amounts
A line is “matched” only when GSTIN + document number align and the tax figures are within your agreed rounding tolerance (often ₹1–₹2 on long invoices). Value matches with a different invoice number are not matches — they are clues.
4. Sort every line into one of five buckets
- Matched: Safe to consider for ITC (subject to Section 16 conditions and your CA’s review).
- In books, not in 2B: Supplier may not have filed, filed under another GSTIN, used a different invoice number, or filed in a later period.
- In 2B, not in books: You missed the purchase entry, booked under the wrong month, or the supplier billed a different branch/GSTIN.
- Partial mismatch: Same invoice identity but taxable value or tax differs (discount not shared, freight split, wrong tax rate).
- Credit / debit notes: Track separately so a credit note does not silently wipe a matched invoice’s credit.
5. Clear gaps with suppliers before you file GSTR-3B
Send each “in books, not in 2B” supplier a short list: GSTIN, invoice number, date, taxable value, tax. Ask whether they filed GSTR-1 for that period and under which document number. For “in 2B, not in books”, find the physical or email invoice and post it — or confirm it belongs to another GSTIN in your group.
6. Decide ITC for this GSTR-3B, then park the rest
Claim only what your process and adviser say is eligible this month. Park unmatched books invoices for follow-up; many appear in a later 2B when the supplier files late. Keep a simple ageing sheet so nothing is forgotten past your internal cut-off.
7. File, archive, and note open items
After GSTR-3B is filed, save the 2B file, the books export, the match sheet and the supplier emails in that month’s folder. Carry open items into next month’s first checklist item.
Typical gaps you will see (with an illustrative Kerala example)
The numbers below are made-up for illustration for a Thrissur grocery that buys from local distributors. They are not industry averages.
Suppose October purchases in the books show 48 B2B invoices with total ITC of ₹1,12,400. GSTR-2B for October shows 44 documents with ITC of ₹1,05,800.
- Matched: 40 invoices, ITC ₹98,200.
- In books, not in 2B: 6 invoices, ITC ₹9,600 — four suppliers filed GSTR-1 after the 2B cut-off; one used invoice number
INV-104in books while the supplier filed104; one invoice was billed to the owner’s other GSTIN in Ernakulam. - In 2B, not in books: 3 documents, ITC ₹4,100 — two credit notes the shop never posted; one invoice still in the “pending entry” tray.
- Partial mismatch: 1 invoice where books show ₹18,000 tax and 2B shows ₹17,820 because a trade discount was on the supplier’s copy only.
Working that list for two afternoons is normal for a busy shop. Skipping it and claiming the full ₹1,12,400 “because we paid the suppliers” is how mismatches stack up.
Late-filing suppliers, wrong GSTIN and other common causes
- Supplier filed late: Their invoice may appear in a later period’s 2B. Keep the books entry; claim when eligible and advised.
- Wrong GSTIN on the invoice: Branch GSTIN vs head-office GSTIN, or an old registration. Fix master data and ask for a revised invoice or credit/debit note as your adviser suggests.
- Invoice number formatting: Leading zeros, prefixes (
GST/,FY/) or spaces that your staff typed differently from the supplier’s GSTR-1. - Credit notes ignored: Returns and rate differences reduce ITC; if you skip posting them, books look higher than 2B.
- Composition or exempt suppliers: You should not expect ITC; remove those lines from the ITC match, not from purchase accounting.
- RCM purchases: Treated differently from forward-charge supplier invoices — do not force them into the same “supplier filed in GSTR-1” mental model without checking the document type.
How clean purchase entries in billing software make reconciliation fast
Most 2B pain is data quality, not portal skill. When every purchase invoice is entered the same day goods land, with the GSTIN copied from the invoice (not from memory), the document number typed exactly, and CGST/SGST/IGST split correctly, your export lines up with 2B in one pass.
Practices that help:
- Supplier master with verified GSTIN (and a quick portal check when you onboard someone new).
- No “misc purchase” dumping ground for taxable B2B buys.
- Credit notes posted against the original invoice reference.
- Separate series or flags for non-GST, composition and RCM documents.
- HSN and tax rate taken from the invoice so value and tax stay consistent.
GST-ready invoicing on the sales side also keeps your outward data tidy for customers who reconcile against your GSTR-1 — see GST billing software for retail shops, GST invoice software for shops and GSTR-1 from billing software.
A simple weekly habit inside the month
Do not wait for month-end. Once a week:
- Enter all pending supplier invoices.
- List any invoice waiting more than seven days for a GSTIN correction.
- Chase suppliers who habitually file late before their due date, not after yours.
Shops that do this often finish formal gstr 2b reconciliation in under a day because the ugly gaps were already cleared.
Where Caddayn Biller fits
If purchase entry and GST billing still live in separate notebooks, a single system helps. Caddayn Biller supports GST billing, barcode billing, inventory with low-stock and reorder alerts, multi-branch use, units of measure, price lists, bulk billing, and UPI/card/cash payments, with Windows and web apps. Vertical ERPs cover supermarket, pharmacy (batch and expiry), restaurant (KOT, tables, split bills, QR ordering) and more. Download the app from caddayn.com/downloads and try the purchase and GST document flow with your adviser before you change process mid-month.
FAQ
Is GSTR-2B the same as GSTR-2A?
No. GSTR-2A is a dynamic view that can change as suppliers file or amend. GSTR-2B is a period statement generated for ITC purposes. Most monthly ITC routines now centre on 2B; confirm the current portal behaviour with your CA.
Can I claim ITC if the invoice is in my books but not in GSTR-2B?
Often you should wait or follow your adviser’s view for that period. Many missing lines appear after the supplier files. Claiming blindly creates avoidable mismatches with GSTR-3B.
What if the supplier uploaded the wrong invoice number?
Ask them to correct through the return amendment process they use (for example GSTR-1A where applicable) or issue credit/debit notes as advised. On your side, keep the physical invoice and a written trail of the mismatch.
Do I reconcile credit notes the same way?
Yes — match note number, GSTIN and tax. Unposted credit notes are a frequent reason books ITC looks higher than 2B.
Does composition scheme change this routine?
Composition dealers generally do not claim ITC the same way regular taxpayers do, and they issue bills of supply. If you are under composition, this full 2B ITC match is usually not your monthly focus — confirm with your practitioner.
Quick checklist before you file
- Books export and 2B download for the same period are saved.
- Every B2B purchase line is matched, parked or explained.
- Credit/debit notes are posted.
- Wrong-GSTIN and invoice-number fixes are requested in writing.
- ITC figure used in GSTR-3B matches the reconciled eligible amount.
This article is for general information for Indian shop owners. It is not tax, legal or filing advice. GST rules, portal behaviour and due dates change — confirm with your Chartered Accountant or GST practitioner before you claim credit or file returns.